Direct answer. To calculate landed cost per activewear SKU, start with the supplier quote’s scope and delivery term, add the freight, insurance, import duty, non-recoverable taxes, clearance, handling and domestic delivery costs that belong to the shipment, then allocate shared charges with a documented driver. Divide each SKU’s allocated total by the units expected to be saleable after receipt checks. Keep retail, marketplace, fulfilment and return costs in a separate margin model.
A landed-cost estimate is only as useful as its inputs. A garment price quoted on one basis may exclude transport or import charges that another offer includes. A shipment total can also hide how much cost belongs to each style, colour or size. If the allocation rule is not written down, two spreadsheets can show different unit costs even when they use the same supplier invoice.
This guide gives a buyer-side worksheet method for private-label and wholesale activewear programmes. It is not a tariff ruling, tax calculation, freight quotation or accounting opinion. Rates, customs value rules, tax treatment, shipment charges and exchange rates depend on the product classification, origin, destination, date, contract and importer. Confirm those inputs with the relevant customs broker, forwarder and tax or finance adviser before using a number for a commercial decision.
The goal is not to make every cost perfectly predictable before a shipment exists. It is to show which numbers are confirmed, which are provisional, who supplied them and what would cause the estimate to change.
What does landed cost per activewear SKU include?
For a buyer, landed cost usually means the product cost plus the costs required to bring the goods to a named receiving point under the agreed shipment plan. Define that receiving point explicitly: a port, a third-party warehouse, a fulfilment centre or the brand’s own location can produce different totals. State whether the figure is per ordered unit, per received unit or per saleable unit.
A working model commonly separates costs into three groups:
| Cost group | Examples to identify | Buyer question |
|---|---|---|
| Product and order scope | Garment quote, approved labels and packaging, samples or development charges if included, inspection agreed for the order | What exact styles, versions, quantities and deliverables are covered by the offer? |
| Shipment and import | Freight, cargo insurance, origin and destination handling, customs brokerage, duty, non-recoverable import tax, documentation and domestic delivery | Which charges are included, excluded, estimated or payable by another party? |
| Allocation and selling model | Shared charges allocated by a chosen driver; marketplace fees, pick-and-pack, storage, returns and promotions tracked separately | Which costs belong in landed inventory cost, and which belong in channel contribution? |
The boundaries vary by accounting policy and contract. Use a consistent internal definition, and ask the finance owner which charges should be capitalized into inventory cost. A supplier’s Incoterm or invoice total is not a substitute for defining the buyer’s own receiving-point model.
The U.S. Department of Commerce’s export landed-cost guidance describes product value, insurance, freight, tariffs, taxes and other fees as relevant components, while warning that estimates can change and additional charges may apply. Treat that as a starting checklist, not a universal destination-country tax formula.
How should I compare EXW, FOB and delivered quote bases?
Write the named delivery term, named place or port, version of the Incoterms rules if used, and the party responsible for each cost and task. EXW, FOB and a delivered term can shift which legs or formalities sit inside the offer. The quote title alone does not tell you whether a customs fee, export handling charge, insurance, destination terminal fee or last-mile delivery is included.
Under the ICC Incoterms 2020 rules, each selected rule allocates defined delivery obligations, costs and risks between seller and buyer. Confirm the exact rule and named location in the contract. FOB is for sea and inland waterway transport; for containerized cargo handed over before it is loaded aboard the vessel, discuss with the forwarder whether FCA better matches the physical handover. The ICC’s Incoterms 2020 checklist can help the parties check the choices that need to be named.
Do not add every possible charge to every quote. Mark each line as included, excluded, paid by seller, paid by buyer, or still unknown. If one quote is FOB and another is delivered to a warehouse, first normalize both to the same destination and responsibility boundary. Ask a forwarder for the missing legs and local fees instead of applying a generic percentage.
A structured activewear manufacturer quote comparison helps align what each supplier priced. This landed-cost worksheet begins after the quote scope is clear: it estimates the path from that price basis to the buyer’s defined receiving point.
Which shipment costs should be confirmed before you calculate?
Collect costs at shipment level before dividing them across SKUs. Ask the supplier, freight forwarder and customs broker to identify the currency, quote date, validity period, shipment mode, origin, destination, charge basis and assumptions. A freight estimate without package dimensions, gross weight, carton count, route or service level may be a placeholder rather than a usable offer.
For each line, record the source and confidence. “Confirmed by broker on date X” is different from “budget placeholder from last season.” Separate one-time project costs from recurring shipment costs. If development, pattern work, lab testing or sample courier charges are included in a supplier quote, decide with the finance owner whether to allocate them to inventory, treat them as period or launch costs, or show them separately. Do not quietly divide a one-time cost across units without recording the decision.
| Line item | Record before using it | Common source or confirmation |
|---|---|---|
| Supplier amount | Currency, product scope, version, quantity breaks, quote date and exclusions | Supplier’s written quotation or pro forma invoice |
| Freight and insurance | Mode, route, shipment dimensions and weight, cover and insured value assumptions | Freight forwarder or insurer |
| Duty and import charges | Classification basis, origin, destination, customs value assumptions, rate source and effective date | Customs broker or official tariff resource |
| Port, terminal and clearance | Origin and destination charges, brokerage, inspection or documentation assumptions | Forwarder, broker and destination agent |
| Domestic delivery | Named receiving location, delivery method, accessorials and appointment needs | Carrier or warehouse |
| FX and bank charges | Currency, conversion source and date, transfer or card charges if the model includes them | Finance policy and payment provider |
For EU imports, the European Commission’s Access2Markets My Trade Assistant lets users search by product or HS code, export country and destination. The Commission notes its database information has limitations and its reports are not official decisions. Verify classification and applicable charges with the competent authority or qualified adviser. For the United States, use current official resources and a broker familiar with the relevant product and entry. Never reuse a rate from an older order just because the garments look similar.
If supplier and logistics inputs are still moving, model a base, higher-cost and lower-cost case using clearly labeled assumptions. The activewear startup budget planning guide can help place inventory cash needs alongside samples, launch work and other startup expenses; do not mix those categories into an SKU landed-cost figure unless your stated policy calls for it.
How do you allocate shared shipment costs across activewear SKUs?
Choose a driver that reflects the cost being allocated, then apply it consistently and document why it fits. Freight may be more closely related to carton volume or chargeable weight than to garment value. Some duties or taxes may depend on customs value and classification. A broker, accountant or internal finance policy should confirm the correct basis for charges that are regulated or subject to specific valuation rules. Do not assume that a single allocation method fits every cost line.
For an internal planning estimate, calculate each pool separately. For example, a shipment may include a freight pool allocated by volume, a brokerage fee divided by entry or line count, and a product-specific charge assigned directly to one style. Keep the calculation visible so that a later change in carton plan or SKU mix can be explained. Do not allocate a charge across goods that did not incur it.
A simple freight allocation by volume might be written as:
SKU share of freight = shipment freight pool × (SKU carton volume ÷ total shipment carton volume)
This is an illustrative management allocation, not a rule for customs valuation, accounting treatment or every carrier tariff. If the forwarder bills by chargeable weight, use the documented chargeable-weight basis when modeling freight. If carton-level dimensions are not yet known, label the placeholder and replace it when the packing plan is confirmed.
Where colours or sizes ship in different carton counts, allocate to the level that your data supports. If a style occupies mixed cartons, use the packing list or warehouse plan rather than assuming every garment takes identical space. For a product-specific duty rate or charge, keep the applicable SKU line separate instead of spreading it evenly across an unrelated assortment.
A bill of materials for activewear helps keep style versions and component scope distinct. The activewear packaging checklist helps gather carton, polybag, label and pack-out details that can change how a shipment is measured or divided. Your final allocation driver should follow the cost evidence and finance policy—not convenience alone.
What denominator should I use: ordered, received or saleable units?
The denominator changes the answer. Ordered units are useful for purchase-order planning. Received units reflect what reached the destination. Saleable units reflect the buyer’s estimate after agreed receiving checks, shortages, damage or holds. If the purpose is to set a wholesale or online price, show which denominator you used and how returns or quality holds are treated. Do not imply that a unit is saleable before it passes the brand’s applicable release checks.
For example, suppose a fictional test shipment has 1,000 ordered garments, 990 physically received and 975 released as saleable after the buyer’s checks. A shipment-level cost divided by 1,000 answers a PO-planning question; divided by 990 it shows cost per unit received; divided by 975 it shows the planning cost across released units. All three calculations can be useful, but they answer different questions. The counts are invented solely to explain the denominator and do not describe an inPACE order.
If you expect shortages or write-offs, keep the assumption visible and test a range instead of hiding it inside a larger unit cost. Record whether replacements, credits or insurance recoveries are included. A later credit should be traced to the shipment and accounting period rather than silently rewriting the original estimate. For a developing range, explain how a sample or development charge is treated separately from bulk goods.
How should landed cost connect to an online selling price?
Landed cost is one input to a selling-price and contribution model; it is not the finished retail price. Depending on the operating model, additional lines may include pick-and-pack, warehousing, marketplace or payment fees, customer delivery subsidy, returns processing, discounts, advertising, customer support and taxes collected at sale. Track those below the landed inventory cost so buyers can see the difference between getting the product to the defined destination and selling it through a channel.
A useful unit-economics worksheet can show: estimated landed cost per saleable SKU; target selling price; variable channel costs; expected discount or return scenario; and contribution before fixed operating expenses. The channel assumptions should be sourced from the actual platform plan, carrier agreement and finance model. A marketplace fee may depend on category, country, plan or date, so do not paste one universal rate into every SKU.
Before using the estimate, run sensitivity checks on the variables most likely to move: freight mode, exchange rate, shipment utilization, duty classification, destination fees, saleable yield and discount level. State the low, base and high cases with the assumption behind each. This makes the price decision more useful than presenting a single exact-looking unit amount from uncertain inputs.
For a consistent scope review, compare the estimate with the private-label activewear for ecommerce guide. It covers the e-commerce product and fulfilment context; this article concentrates on the cost bridge from supplier basis to destination. Confirm that the product direction itself is clear before treating any spreadsheet as a quote.
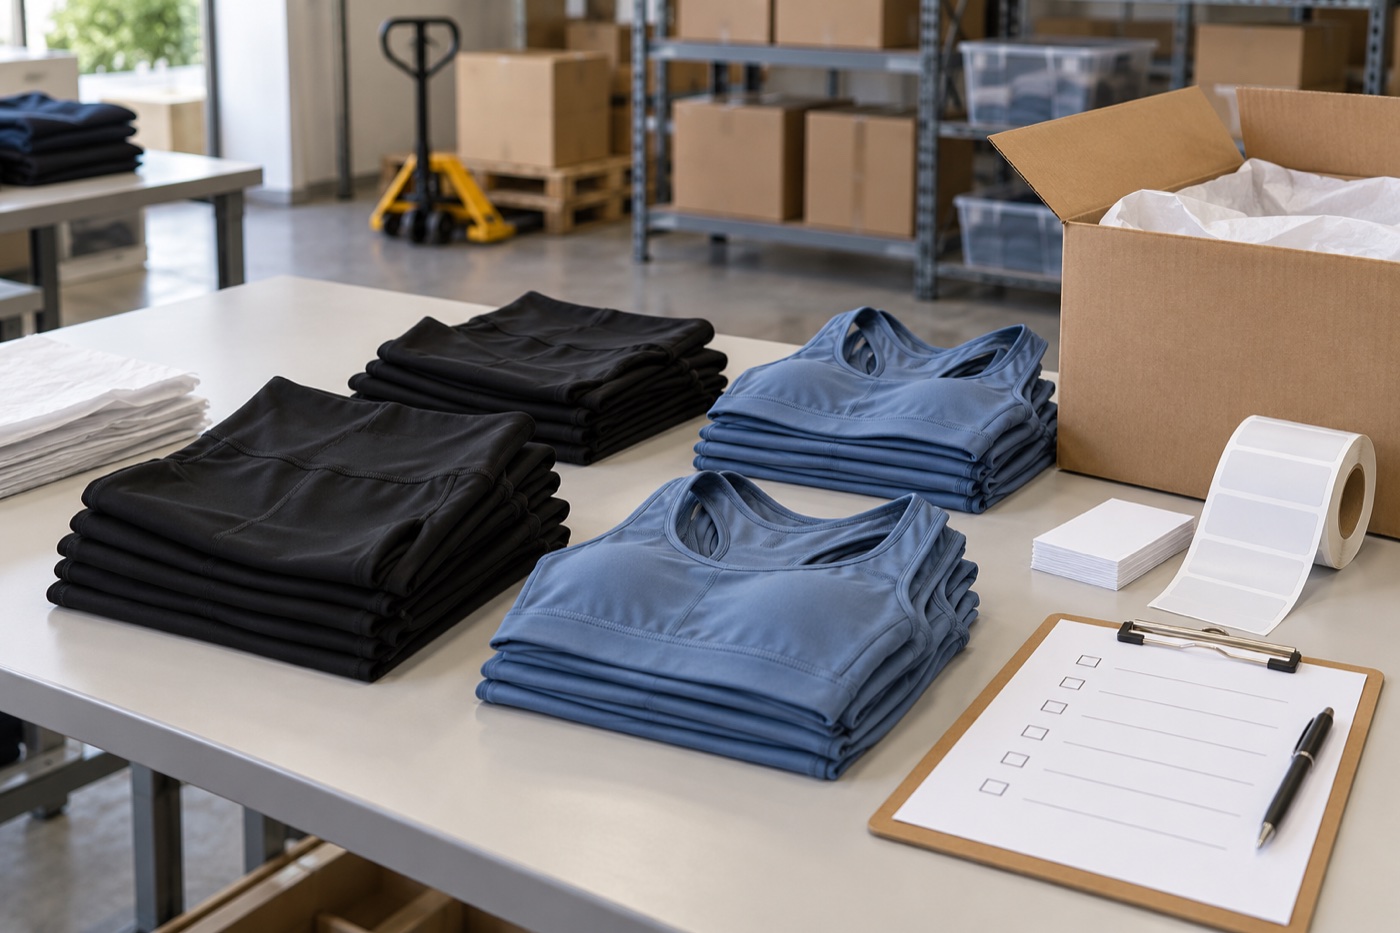
*Use the pack-out and carton plan to identify which shipment costs can be assigned directly and which need a documented allocation driver.*
What should a landed-cost worksheet contain?
Set one row per style-colour-size SKU, then connect it to a shipment-level cost table. Preserve stable identifiers: product code, description, colour, size, supplier quote reference, approved product version, currency, unit of measure and quantity. Keep a separate field for planned, ordered, received and saleable quantities so that a change in denominator does not break the source data.
A practical worksheet can include these fields:
- SKU identifier, style, colour, size and approved revision.
- Supplier unit amount, currency, quote date, quote basis and included scope.
- Quantity status: planned, ordered, received, accepted or on hold.
- Direct costs assigned to one SKU and the source document for each.
- Shared cost pool, allocation driver, SKU share and formula.
- Duty, non-recoverable tax and clearance assumptions, with source and effective date.
- Freight, insurance, handling and delivery estimates with quotation references.
- FX source, conversion date and bank-charge treatment if applicable.
- Landed cost per ordered, received and saleable unit, clearly labeled.
- Open questions, owner, next review date and scenario status.
Build a subtotal before applying allocation so another reviewer can retrace the math. Lock the input cells or use a version-controlled template when multiple people contribute. Do not overwrite the supplier’s original quote; link the document and record which assumptions the model added. If an estimate is revised, retain the prior version or the date and reason for the update.
This is also a useful place to connect the cost sheet to the activewear purchase order checklist. The PO and worksheet should refer to the same approved styles, quantities, materials and pack-out assumptions, even though the documents answer different operational questions.
What should be checked before an online price is approved?
Before setting a price, ask whether the product scope, shipment basis and selling assumptions describe the same scenario. A quote for one material or packaging level cannot be combined with freight from a different pack-out without a note. An estimated tariff should not be treated as final. A saleable-unit denominator should show how shortages or holds were considered. A marketplace margin should use the channel terms that apply to the intended market.
Use this review checklist with the buying, operations and finance owners:
- Confirm supplier quote version, quote basis, included work and exclusions.
- Name the agreed delivery term, named place and cost responsibility split.
- Confirm SKU mix, carton count, dimensions, gross weight and shipment mode assumptions.
- Identify who validates classification, customs value, duty and tax treatment.
- Date every freight, FX, insurance and import-cost source.
- Separate direct charges from pooled charges and record each allocation basis.
- Show cost per ordered, received and saleable unit where those differ.
- Keep one-time development or launch spending visible outside recurring unit cost unless finance directs otherwise.
- Add channel, fulfilment, discount and return costs in the separate contribution model.
- Assign an owner and review trigger for each provisional assumption.
When the product brief or packing details are incomplete, return to the manufacturer quote comparison guide and resolve the scope questions first. For a project-specific discussion, share the styles, quote basis, destination, packing plan and known assumptions through the inPACE contact page. The team can review whether the manufacturing brief and supplied cost inputs are clear enough to discuss; a project response does not replace a customs broker’s or finance adviser’s determination.
The private-label activewear route is relevant when branding and packaging need to be aligned to an existing product direction. Keep fabric, construction and product decisions connected to the current approved version so the cost model follows the same item the buyer intends to sell.
Product directions
Explore relevant activewear products
Use these product pages as practical references for your brief, then confirm materials, fit, customization, and production details through sampling.
Private Label Activewear
Align branding and packing scope with an identified product direction and the assumptions in your buyer worksheet.
View product directionActivewear Manufacturing
Discuss the production and shipment scope behind a buyer-defined activewear brief.
View product directionWholesale Activewear Supplier
Review an existing-style sourcing route and confirm current product, packing and order details for the project.
View product directionFAQ
Buyer questions
What is landed cost per SKU?
It is the defined product and shipment cost assigned to one stock-keeping unit at a stated destination, divided by a clearly identified unit count. Buyers should state whether the denominator is ordered, received or saleable units and document how shared charges are allocated.
Does landed cost include marketplace fees and returns?
Those are normally tracked in a separate selling or contribution model because they occur after goods reach the defined destination. A business may adopt its own accounting policy, so identify the boundary and ask the finance owner which costs belong in inventory cost.
How do I allocate freight across apparel SKUs?
Use a documented driver that reflects the charge, such as carton volume or chargeable weight for a freight pool, then apply it consistently. Directly assign SKU-specific charges where possible and confirm regulated valuation or accounting treatments with the relevant adviser.
Should I divide shipment costs by ordered or saleable units?
Both can be useful for different decisions. Ordered units support purchase planning, received units show the result at destination, and saleable units account for the buyer’s release status. Label the denominator and show shortages or holds rather than hiding them.
Can I use the supplier’s FOB price as my landed cost?
No, the quote basis must be connected to your named receiving point. Confirm what the exact Incoterm and named place include, then add the buyer-paid shipment and import costs that are not included. Ask a forwarder or broker to confirm the missing legs and charges.
Where can I find the duty rate for activewear?
The applicable rate depends on product classification, origin, destination, date and other conditions. Start with the destination’s official tariff resource, then confirm classification and treatment with a qualified customs broker or the competent authority before using the estimate commercially.
How often should I update a landed-cost estimate?
Update it when the supplier quote, Incoterm, shipment route, carton plan, quantity mix, currency, customs assumptions, destination charges or saleable-unit forecast changes. Record the source date and keep provisional assumptions visible until replaced with confirmed inputs.
Is an online landed-cost calculator accurate for every order?
A calculator can organize inputs but cannot validate an incorrect product code, quote scope, charge basis or tax treatment. Use it as an estimate, retain the assumptions and source dates, and have the appropriate broker and finance adviser confirm the inputs for the actual shipment.